Events
Peter Bergan to Moderate Panel at TMT Finance USA 2026
Partner Peter Bergan will moderate a panel at TMT Finance USA 2026 on October 6 titled “How is Datacenter Powered …
October 6, 2026
October 6, 2026 • 1-minute read

Insight
Client Alerts
V&E SEC Update
Update: On December 19, 2023, the U.S. Court of Appeals for the Fifth Circuit vacated the Securities and Exchange Commission’s share repurchase modernization rules that are the topic of this article. As a result, public companies do not need to comply with the disclosure requirements of the share repurchase disclosure modernization rules.
May 8, 2023 • 11-minute read
Final rules to modernize share repurchase disclosure will go into effect for the first periodic report that covers the first full fiscal quarter that begins on or after October 1, 2023. For calendar-year companies, that first report will be the Form 10-K filed in early 2024 for fiscal year 2023.
In summary, the new rules apply to almost all reporting companies and require quarterly disclosure of the following:
The new disclosures must be tagged using inline XBRL.
After proposing amendments to the disclosure requirements regarding share repurchases (also known as share buybacks) in December 2021 and re-opening the comment period for the proposed rules in December 2022, the Securities and Exchange Commission (the “SEC”) adopted its final rules to modernize share repurchase disclosure (the “Final Rules”) on May 3, 2023. The SEC noted in the adopting release that the Final Rules are intended to provide investors with more detailed information so that they may better assess the motivations for companies’ repurchase plans or programs and may determine whether repurchase activity lines up with companies’ stated rationales or instead serves other purposes, such as those related to executive compensation and accounting metrics, such as earnings per share.
The Final Rules do not provide any exemptions and apply to all issuers of securities that are registered pursuant to Section 12 of the Securities Exchange Act of 1934 (the “Exchange Act”), other than Canadian companies that report under the MJDS.1 The Final Rules generally require reporting companies to do the following:
The Final Rules amend Item 601 of Regulation S-K (“Reg. S-K”) to require companies to file new Exhibit 26 with their Form 10-Qs and Form 10-Ks. Exhibit 26 will disclose, for the period covered by the report (or the company’s fourth quarter for the Form 10-K), the total purchases of shares of the company’s equity securities registered pursuant to Section 12 of the Exchange Act made each day by or on behalf of the company or an “affiliated purchaser.” The Final Rules also eliminate the current requirements under Item 703 of Reg. S-K to disclose monthly repurchase data within periodic reports. The disclosure in Exhibit 26 must be in tabular format and include the following information:
The SEC provided this example table in the Final Rules:
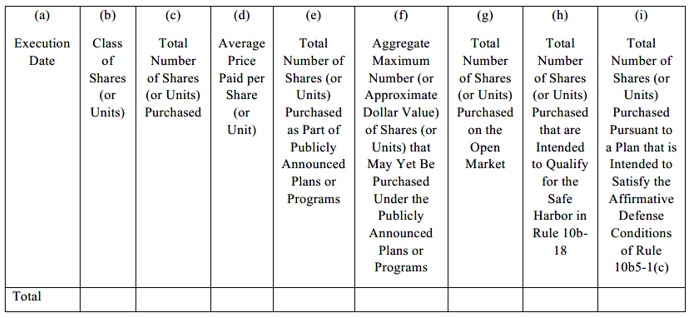
The table must also include footnotes regarding the adoption or termination date of any Rule 10b5-1 plans referenced in column (i).
Although the Final Rules require disclosure of the daily repurchase data, companies must report the daily data quarterly in Forms 10-Q and 10-K. This is a significant improvement over the proposed rules, which would have required companies to provide daily public reports during active programs by furnishing a new Form SR one business day after the date that the company (or affiliated purchaser) executed such a purchase.6
On the other hand, the Final Rules require that daily repurchase information be filed with the SEC in Forms 10-Q and 10-K rather than being furnished in a Form SR as originally proposed. As a result, (a) companies will be subject to liability under Section 18 of the Exchange Act for the information, (b) the information will be deemed incorporated by reference into registration statements for offers and sales under the Securities Act of 1933 (the “Securities Act”) (e.g., registration statements on Forms S-1 and S-3), and (c) companies will therefore be subject to liability for the information under Section 11 of the Securities Act. The SEC determined that, because companies will be required to disclose the daily repurchase data on a quarterly basis, they will have more time to obtain, verify, and compile the data. Thus, liability concerns raised by the proposed one-business-day timeframe will be “alleviated.”7
New Exhibit 26 includes a box that companies must check if any of their directors or officers reporting pursuant to Section 16 of the Exchange Act purchased or sold shares of a class of the company’s equity securities that are registered pursuant to Section 12 of the Exchange Act and subject to a company repurchase plan or program within four business days before or after the company announced the plan or program or an increase of the existing plan or program. In determining whether to check the box, companies are permitted to rely on certain filings/documents unless they know or have a reason to know that such filings were filed inappropriately or that a filing should have been made but was not. These include Forms 3 and 4 and amendments thereto filed with the SEC during the company’s most recent fiscal year, Forms 5 and amendments thereto filed with the SEC with respect to the company’s most recent fiscal year, and any written representation from the reporting person that no Form 5 is required (which the company must maintain in its records for two years and make available to the SEC upon request).
The Final Rules do not define “purchase” or “sale” for this purpose. The reference to reports required under Section 16 of the Exchange Act (“Section 16 Reports”) as the primary basis for the company’s decision whether to check the box might suggest that any transaction required to be reported on Section 16 Reports may be a purchase or sale, but it might suggest that only transactions that constitute a purchase or sale under Section 16 rules are relevant (gifts, for example, would not be a sale, even though reported on Section 16 Reports). Arguably, only open market purchases or sales should be relevant. Absent clarification from the SEC, companies will have to determine what is a disclosable purchase or sale in this context.
Some market participants may infer from a checked box that a purchase or sale should not have been made during the four business days before or after a specified announcement about a repurchase plan or program, as some comment letters noted. We expect companies will evaluate whether to prohibit at least discretionary purchases and sales during the eight business days that would trigger a checked box.
The Final Rules require that companies indicate whether directors and officers reporting pursuant to Section 16 of the Exchange Act have engaged in certain equity transactions within four business days of a company repurchase plan or program announcement, rather than 10 business days as was initially proposed. The SEC noted that the originally proposed 10-day period would result in added attention to certain transactions that are insignificant, thereby reducing the value of the checkbox. The Final Rules also require disclosure where such transactions are made within four business days of the announcement of an increase of an existing share repurchase plan or program, which was not included in the proposed rules. Finally, the Final Rules provide new clarification of the filings/documents on which companies may rely in determining whether to check the box.
The Final Rules add requirements for companies to make quarterly narrative disclosure regarding their repurchase programs and practices within their periodic reports. Accordingly, pursuant to revised Item 703 of Reg. S-K, companies are required to disclose in narrative format, referring to corresponding repurchases in the new Exhibit 26 table where applicable:
While the Final Rules’ treatment of Item 703 of Reg. S-K differs to a large extent from that of the proposed rules, the actual substance of the SEC’s proposed changes to Item 703 of Reg. S-K largely remains in the Final Rules, albeit with different placement and formatting (e.g., disclosure of the number of shares purchased and intended to qualify for the affirmative defense conditions of Rule 10b5-1(c) or Rule 10b-18 of the Exchange Act is required in new Exhibit 26 rather than pursuant to Item 703 of Reg. S-K).8
After omitting certain company-related disclosures from the final rules adopted regarding insider trading arrangements and related disclosure in December 2022, the SEC used the Final Rules to finish the job with amendments to Item 408 of Reg. S-K. Much like the SEC’s new requirements for companies to disclose certain information regarding the trading arrangements of their directors and officers under Item 408(a) of Reg. S-K, the Final Rules require disclosure of whether the company itself adopted or terminated during the quarter covered by the report (or the fourth quarter for the Form 10-K) any “Rule 10b5-1 trading arrangements” as the term is defined in Item 408(a)(1)(i) of Reg. S-K9 (“Rule 10b5-1 Plans”). If so, companies are required to disclose “material terms” regarding their Rule 10b5-1 Plans, including (a) the date on which the company adopted or terminated a Rule 10b5-1 Plan; (b) the duration of the Rule 10b5-1 Plan; and (c) the aggregate number of securities to be purchased or sold pursuant to the Rule 10b5-1 Plan. The Final Rules state that the material terms to be disclosed regarding such Rule 10b5-1 Plans do not include terms with respect to the price at which the party executing the Rule 10b5-1 Plan is authorized to trade. If a company’s disclosure made pursuant to Item 703 of Reg. S-K would satisfy these requirements, it may simply cross-reference to such disclosure.
The proposed rules did not contemplate these disclosure requirements regarding company Rule 10b5-1 Plans, but the Final Rules largely track the SEC’s proposed rules regarding insider trading arrangements and related disclosure regarding company Rule 10b5-1 Plans which, as previously mentioned, were not included in the SEC’s final rules adopted in December 2022 regarding insider trading arrangements and related disclosure.
Like the proposed rules, the Final Rules will require all of the newly required disclosure to be tagged using inline XBRL.
Companies are required to comply with these new disclosure requirements, including providing the daily repurchase data table and checkbox within new Exhibit 26 to their Forms 10-Q and 10-K, the narrative disclosure regarding share repurchase plans or programs and company Rule 10b5-1 Plans in their Forms 10-Q and 10-K, and the related tagging requirements, beginning with the first filing that covers the first full fiscal quarter that begins on or after October 1, 2023. For calendar-year companies, this will be the Form 10-K for fiscal year 2023 to be filed in early 2024.10
In preparing for compliance, companies should take several items into consideration:
The V&E team is available to provide more in-depth education about the Final Rules and steps to prepare for future compliance.
1 The SEC notes that it is not imposing the new requirements on Canadian issuers that file using the Multijurisdictional Disclosure System, or MJDS, because those issuers are subject to a separate reporting regime. See Final Rule: Share Repurchase Disclosure Modernization, SEC Release No. 34-97424 (May 5, 2023) (“Adopting Release”), at 58.
2 For Listed Closed-End Funds, this disclosure must be made on a semi-annual basis on Form N-CSR and for Foreign Private Issuers (“FPIs”), this disclosure must be made in a new Form F-SR that must be filed within 45 days after the end of the FPI’s fiscal quarter. For more information on the reporting requirements applicable to Listed Closed-End Funds and FPIs, please contact your V&E attorney.
3 See Footnote 2 regarding the timing/form of disclosure for Listed Closed-End Funds and FPIs.
4 Rule 10b-18 provides a company and its affiliated purchasers a non-exclusive safe harbor from liability under certain market manipulation rules when repurchases of the company’s securities are made in accordance with the conditions set forth in Rule 10b-18.
5 A trading plan that satisfies the conditions of Rule 10b5-1(c) can be used as an affirmative defense against potential insider trading liability.
6 Note, however, that FPIs will still be required to disclose daily repurchase data on a quarterly basis in the new Form F-SR. See Footnote 2 above.
7 See Adopting Release at 57.
8 Note that the Final Rules slightly tweak the language regarding purchases made with reference to Rules 10b5-1(c) and Rule 10b-18 to address commenters’ concerns that companies are able only to indicate their intent to satisfy/comply with the affirmative defense conditions/safe harbor provided by such rules. See Adopting Release at 61.
9 Item 408(a)(1)(i) of Reg. S-K defines “Rule 10b5-1 trading arrangements” as any contract, instruction or written plan for the purchase or sale of securities of the company intended to satisfy the affirmative defense conditions of Rule 10b5-1(c) of the Exchange Act.
10 FPIs that file on foreign private issuer forms must disclose the daily repurchase data in new Form F-SR beginning with the Form F-SR that covers the first full fiscal quarter that begins on or after April 1, 2024, and provide the narrative disclosure starting in the first Form 20-F filed after their first Form F-SR has been filed. Registered closed-end management investment companies that are exchange traded will disclose the quantitative data and provide the narrative disclosure on Form N-CSR beginning with the Form N-CSR that covers the first six-month period that begins on or after January 1, 2024.
This information is provided by Vinson & Elkins LLP for educational and informational purposes only and is not intended, nor should it be construed, as legal advice.
Discover our latest:
Events
Peter Bergan to Moderate Panel at TMT Finance USA 2026
Partner Peter Bergan will moderate a panel at TMT Finance USA 2026 on October 6 titled “How is Datacenter Powered …
October 6, 2026
October 6, 2026 • 1-minute read
CLE Events
Texas Reincorporation 101: Recent Developments and Key Considerations for Boards
Join Vinson & Elkins and FTI Consulting for a webinar on the growing trend of companies reincorporating to Texas.
October 1, 2026
October 1, 2026 • 1-minute read

CLE Events
Financing and Bankability of Data Center Projects
This program will examine the key legal and commercial considerations for financing data center projects, with a focus on what makes these projects bankable for lenders and investors.
September 29, 2026
September 29, 2026 • 1-minute read

Events
Paige Anderson to Speak on BARBRI Webinar
Partner Paige Anderson will speak on BARBRI’s live video CLE program, “Mastering Public and Private REITs: Key Tax, Structuring, Financing, …
September 22, 2026
September 22, 2026 • 1-minute read

Events
Partners Paige Anderson and Vinay Prabhakar will present on myLawCLE’s live CLE program, “REIT Tax in the Data Center Era: …
September 18, 2026
September 18, 2026 • 1-minute read

Thoughts or questions? Send us a note, and we’ll connect you with the right person.